How to Prepare Emergency Cash and Payment Backups for a Long Outage
Create a modest, usable payment reserve that still works when card terminals, ATMs, banking apps, or one financial provider become unavailable.
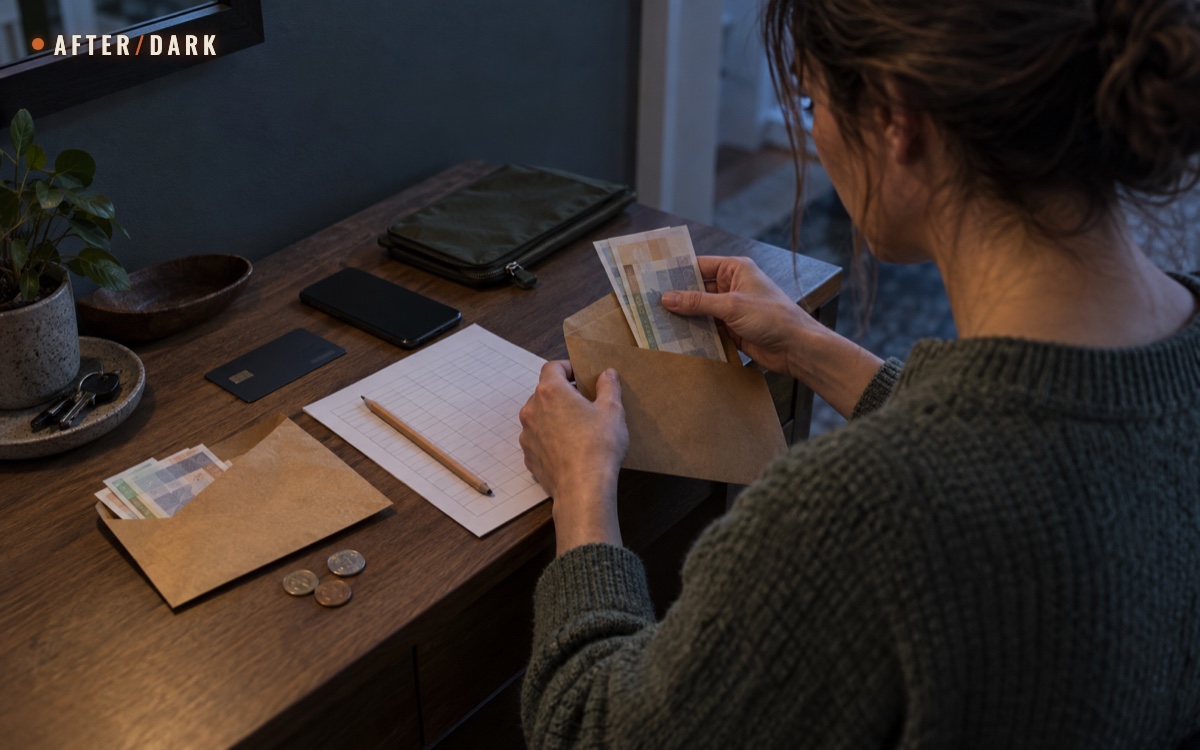
Short answer
Key takeaways
- Calculate the reserve from uncovered essential purchases and current local prices; there is no useful universal cash amount for every household.
- Choose denominations from the transactions you expect to make, because a large note is not useful when a seller cannot provide change.
- Use three separate layers: spendable cash, an independent payment option, and protected offline contact information.
- Keep full account credentials, PINs, passwords, and security codes out of the cash module and its operating card.
- Track every withdrawal and refill the reserve after use so the amount on the household card always matches the amount available.
Prepare emergency cash and payment backups by listing the essential purchases your stored supplies do not cover, pricing those transactions locally, and reserving denominations that fit them. Add a genuinely independent payment method and a protected offline card with official provider contacts. Keep passwords, PINs, and security codes elsewhere. The complete system should work without power or internet access, show who may retrieve each part, and make every use easy to record and replace.
This is a transaction-continuity plan, not a recommendation to keep a universal sum at home. The right amount depends on the household, the planned operating window, available supplies, local prices, transport, and which businesses can still trade. Cash is one layer, not a guarantee: a closed store, unavailable stock, or inaccessible route cannot be solved by adding more notes to an envelope.
The American Red Cross explains that a prolonged power outage can disrupt stores, banks, transportation, and communications as well as household electricity. Connect this payment module to the broader home power outage plan, then give it its own calculation, access rules, and test.
Define What the Payment Plan Must Do
The plan has one narrow job: keep a household able to complete a short list of essential, available transactions when normal payment access becomes unreliable.
That failure can occur at several layers:
- a building or shop has no power;
- a card terminal has power but no network connection;
- an ATM or local branch is unavailable;
- one bank, credit union, card, or payment application has an outage;
- the phone containing the wallet application or contact details is depleted;
- the household can reach its money but cannot retrieve the information needed to resolve a problem;
- cash is accepted, but the seller cannot provide change for a large note.
Do not treat every failure as identical. A second card might help during one provider's outage, but it does not solve a dark terminal. Cash may work at an operating local business, but it does not make a closed store reopen. A printed phone number may restore access to information, but it is not a payment method.
Payment Dependency Map: record what each layer requires before calling it a backup.
| Payment layer | Dependencies | Failure it can cover | Failure it cannot cover |
|---|---|---|---|
| Cash in usable denominations | Physical access, seller acceptance, available stock | Terminal, network, phone, or single-bank outage | Closed seller, blocked route, exhausted local stock |
| Existing independent payment | Its own provider, account access, acceptance, power/network | Failure limited to another provider or instrument | Broad power or communications failure |
| Offline provider reference card | Physical access, readable current information | Lost phone access or forgotten contact details | Lack of a working contact channel or spendable funds |
| Household transaction log | Paper and writing tool | Uncertain balance and duplicated spending | Missing reserve, inaccessible seller, or invalid payment |
The Consumer Financial Protection Bureau advises contacting the institution and trying other available methods when a bank or credit union has an outage. The practical lesson is dependency diversity: label what each layer needs, then make sure the layers do not all depend on the same phone, provider, account, or network.
Start With Uncovered Purchases, Not a Round Number
Begin with the household's existing supplies. If water, shelf-stable meals, batteries, transport arrangements, and other essentials are already available, do not count them again as expected purchases. Use the home supply organization system to confirm what is present, usable, and reachable before calculating money.
Create a list containing only transactions that meet all four conditions:
- Necessary: the household has a clear reason to complete the transaction during the planned outage window.
- Not already covered: the item or service is not available in the home reserve or through an existing arrangement.
- Realistically available: a likely seller, service, or route could still operate under the assumed conditions.
- Priceable now: the household can record a current local price, fare, fee, or reasonable range.
Possible categories include local transport, an approved destination, an ordinary supply refill, ice for a prepared cold-storage plan, a routine household service, or another locally relevant purchase. These are prompts, not a universal shopping list. Delete any line that does not belong to the household's actual plan.
Uncovered Purchase Worksheet: use current local prices and remove anything already supplied.
| Essential transaction | Unit or fare | Current local price | Planned quantity | Planned subtotal | Why it remains uncovered |
|---|---|---|---|---|---|
Price the unit that will actually be sold. A plan for “transport” is not costed until it records the number of fares, trips, or another locally valid unit. A plan for “supplies” is not costed until the quantity and likely seller are known.
Do not build the total from fear, a social-media number, or the largest amount the household could withdraw. A large unexplained reserve is harder to verify, harder to divide, and easier to count as available for several purposes at once.
Choose the Operating Window Before Calculating the Reserve
“Long outage” describes uncertainty, not one standard duration. Choose the payment window from the household operating plan:
- the first overnight period;
- the first three days;
- the interval until a verified destination becomes available;
- the interval until an existing supply or transport arrangement changes;
- another clearly defined phase with a written transition trigger.
The payment reserve does not need to fund every possible purchase for the entire disruption. It needs to bridge the household through the phase it has deliberately planned. If the outage continues beyond that phase, the written plan should change location, supply method, or payment access rather than assume an envelope can solve an unlimited disruption.
Calculate the working amount as:
Cash target = sum of planned cash-capable transactions within the chosen window
For each line:
Planned subtotal = current local unit price × planned quantity
Add a fee only when it is known and relevant. If a price is variable, record a current high and low observation and state which one the plan uses. Do not disguise an arbitrary percentage as an official safety margin.
Worked Example: fictional local-currency values show the method, not a recommended amount.
| Planned transaction | Calculation | Subtotal |
|---|---|---|
| Four local transport fares | 4 × 3 units | 12 units |
| Three bags of ice | 3 × 5 units | 15 units |
| Two basic supply refills | 2 × 12 units | 24 units |
| Calculated target | 12 + 15 + 24 | 51 units |
The example household would next choose denominations that can make the listed payments. It would not copy “51” into another household's plan without repeating the local calculation.
Match Denominations to the Expected Transactions
The Government of Canada's current emergency-kit checklist includes cash in smaller bills and coins. Apply that guidance through the purchase worksheet rather than using a generic ratio.
For every expected transaction, ask:
- What is the likely total?
- Is exact payment customary or required?
- What denominations are common and accepted locally?
- Would the largest note force the seller to provide most of the reserve as change?
- Are coins genuinely useful for the planned fare or service?
Build the denomination mix transaction by transaction. If a fare is 3 units and four fares are assigned to the plan, allocate four usable combinations rather than one large note worth 12. If a planned purchase is likely to cost 15, do not automatically reserve only a 50-unit note. Keep larger denominations only when they correspond to a realistic purchase and are routinely accepted in the location.
Denomination Worksheet: each row should complete one planned transaction without depending on change.
| Transaction | Expected total | Assigned denominations | Exact payment possible? | Module |
|---|---|---|---|---|
Use current, accepted currency in serviceable condition. Check local rules and exchange practices when the plan crosses a border or uses more than one currency. The article cannot determine what a particular seller is required or willing to accept.
Build Three Independent Payment Layers
A resilient payment plan has three layers with different dependencies.
Layer 1: spendable cash
This is the amount derived from the worksheet, divided into denominations that fit assigned transactions. It is operating cash for the defined outage phase, not a substitute for a broader savings plan.
Record:
- total by module;
- denomination count;
- assigned purchase categories;
- authorized household access;
- last verification date;
- transaction-log location.
Layer 2: an existing independent payment option
Choose an option the household already holds and understands. It is independent only when it removes a meaningful shared dependency. A second physical card linked to the same inaccessible account may not help. Two wallet applications on one depleted phone are not independent. A check is not useful where checks are not accepted.
Record the dependency rather than promising success:
- provider or institution;
- physical or digital access method;
- device, network, or identification needed;
- where it is normally accepted;
- official contact route if it fails.
Do not acquire a financial product merely to complete a preparedness checklist. Confirm available options, terms, and current access directly with the relevant institution.
Layer 3: protected offline references
The CFPB recommends gathering account and customer-service information and keeping protected copies in separate places. For the compact payment card, keep only the minimum needed to identify and contact the provider:
- institution or provider name;
- official customer-service number;
- short label identifying the household's payment method;
- last four digits or another minimal reference when useful;
- the location of the protected full record.
Do not place a PIN, password, complete security code, recovery phrase, or unnecessary full account number in the cash envelope. The broader emergency document kit owns protected financial records and access controls; the payment card should point to that system rather than duplicate it.
Separate the Reserve by Function Without Counting It Twice
One reserve may need to support home operation and departure, but the same notes cannot exist in both places on paper.
Use distinct modules:
- Home operating module: assigned to transactions made while the household remains at home.
- Portable module: the smaller portion already assigned to the departure plan.
- Transaction log: one record showing the total, both module balances, and every movement between them.
If the portable module belongs with a bug-out bag, record that amount as part of the total payment reserve. Do not add the full home amount and then describe the portable amount as an extra backup unless it is physically separate money.
Choose storage that is secure, dry, discreet, and accessible to authorized household members. Use an opaque, moisture-resistant inner container, but do not advertise the contents with an external “cash” label. Keep access instructions private and proportionate to the household's existing security practices. The exact location should not appear on a card carried publicly.
The reserve should also be physically distinct from ordinary spending money. If it shares a wallet, drawer, or envelope with daily cash, the recorded balance will drift without anyone noticing.
Write One Household Payment Card
The payment card is an operating index, not a credential sheet. Keep it brief enough to read in dim conditions and structured enough that another authorized person can follow it.
Household Payment Card: complete one protected copy for the home plan and one limited copy for the portable module when needed.
| Field | What to record |
|---|---|
| Plan version | Review date and initials of the person who verified the reserve |
| Operating window | The outage phase this payment plan is designed to bridge |
| Home module | Total, purchase categories, and protected retrieval instruction |
| Portable module | Total, assigned carrier or bag, and purchase categories |
| Independent payment layer | Method label, dependencies, and normal acceptance limits |
| Official contacts | Provider names and verified customer-service numbers |
| Protected records | Location reference for the separate emergency document system |
| Transaction log | Date, purpose, module, amount removed, amount returned, balance |
| Reset trigger | After any use, access change, price review, or household-plan change |
The CFPB disaster checklist provides fields for account and customer-service information and recommends securing copies of important financial records. Use its broader record structure in the protected document kit. Keep the outage payment card deliberately smaller.
Before printing or writing the card, verify provider numbers through an official statement, the physical payment instrument, or the provider's official website. Do not copy contact details from an unsolicited message.
Use and Record the Reserve During an Outage
Activate the payment module only when the household operating card reaches its written trigger. Then follow one sequence:
- Confirm the need. Check that the purchase is assigned, still necessary, and not already covered by available supplies.
- Confirm availability. Use a reliable local source or direct contact when possible before traveling. Do not assume a seller, route, or service is operating.
- Confirm payment acceptance. Ask what methods are currently accepted without sharing the amount carried.
- Take the transaction amount. Remove the assigned denominations rather than carrying the entire home reserve.
- Record the withdrawal. Write the date, purpose, module, amount removed, and remaining balance.
- Retain evidence. Keep the receipt when one is available; otherwise record the completed total manually.
- Return and reconcile. Count change privately, update the balance, and return unused money to the correct module.
If the problem is limited to one financial institution, use its verified contact route. The CFPB advises using the number printed on the card or statement and warns against sharing account or personal information in public social-media posts. Record the outcome, but do not copy sensitive conversation details into the general household log.
Never reveal the size or storage location of the remaining reserve to complete a routine purchase. Carry only what the transaction requires and keep the household total private.
Run a No-Spend Verification Drill
Test access and arithmetic without creating an unnecessary purchase. A useful drill can be completed at home:
- Choose one line from the uncovered-purchase worksheet.
- Ask the assigned household member to retrieve the correct module using the protected instruction.
- Select the denominations that would complete the transaction.
- Fill in a temporary transaction-log line.
- Identify the independent payment layer and state what it depends on.
- Locate the verified provider contact without unlocking the primary phone.
- Recount the module, cancel the temporary transaction, and restore the original balance.
After/Dark uses five minutes as a practical editorial retrieval target, not an official standard. The important result is that an authorized person can find the correct module, produce the assigned amount, locate official contact information, and return the system to its recorded state without searching several rooms or asking the organizer what to do.
Fail the drill if:
- the reserve total does not match the card;
- the required denominations are missing;
- only one person can find or reconcile the module;
- the alternate method shares every dependency with the primary method;
- the contact number is outdated or came from an unverified source;
- the card exposes credentials that do not belong in the operating module;
- the portable amount is also counted as present in the home module.
Correct the failure immediately, then repeat only the failed step.
Maintain and Reset the System
Review the payment plan when:
- any money is used or moved;
- a provider, card, account, phone, or household member changes;
- the household moves or changes its likely transport and destinations;
- stored supplies expand or shrink;
- a planned seller, fare, fee, or local price changes materially;
- an actual outage exposes a missing transaction or shared dependency.
The Government of Canada's emergency-kit guidance suggests reviewing supplies around the seasonal clock change. A twice-yearly payment review is therefore a practical schedule where that seasonal reminder is relevant, but it is not a universal requirement. Use another recurring date if local clocks do not change.
At each review:
- repeat the uncovered-purchase calculation;
- compare recorded and physical balances;
- verify denominations and currency condition;
- confirm official provider contacts;
- test authorized retrieval;
- replace the signed review date on the card;
- reconcile the home and portable modules to one total.
After any real use, reset the reserve before considering the system ready again. A receipt in an empty envelope is a record of failure, not a backup.
Fix the Common Payment-Plan Failures
The amount is a round guess
A memorable number is not evidence. Rebuild it from named purchases, current prices, quantities, and the defined operating window.
Most of the reserve is one large note
The total exists, but the first seller may not be able to make change. Reallocate denominations from the transaction worksheet.
Every backup depends on one phone
The card, wallet application, provider contact, and account details disappear together when the phone is unavailable. Move the minimum contact layer to protected paper and identify a payment method with different dependencies.
The operating card contains full credentials
Convenience has created a privacy risk. Remove secrets and unnecessary complete account numbers; point to the separately protected document system.
The home and portable amounts are both counted in full
The written reserve is larger than the physical reserve. Use one ledger with separate module balances and one combined total.
Nobody records small withdrawals
The envelope slowly stops matching the plan. Require a log entry and immediate reconciliation for every movement, including money returned as change.
Cash is treated as guaranteed access
The plan assumes every business remains open and accepts the available denomination. Add availability and acceptance checks before travel, plus a written transition when the transaction cannot be completed.
Zombie Scenario: The Store with a Dark Terminal
Fictional scenario
On the second evening, the neighborhood still has no stable power. A small food shop opens for a short period, but its card terminal cannot connect. The handwritten sign says cash is accepted while stock lasts.
The household does not carry its complete reserve to the shop. The operating card assigns this trip to the home module and lists two specific refill items. One person confirms the shop is open, removes the denominations already matched to the expected total, and records the withdrawal before leaving.
The purchase costs slightly less than planned. The shopper returns with the items, receipt, and change. The household reconciles the envelope, updates the remaining balance, and leaves the portable module untouched. No one tries to add unplanned purchases simply because cash is available.
By the next morning, the terminal works again, but the exercise has exposed one weakness: the provider number on the offline card is no longer current. The household verifies the correct number through an official statement, replaces the card, and marks the plan for a complete review after normal service returns.
The fictional pressure changes the atmosphere, not the method: define the transaction, carry only the assigned amount, record the result, and correct the system after use.
Complete the Emergency Payment Plan
The plan is complete when the household can answer every line below:
- Which outage phase does the reserve cover?
- Which essential purchases remain after stored supplies are counted?
- What current local price and quantity support each subtotal?
- Which denominations complete those transactions without depending on change?
- Which existing payment option removes a real dependency?
- Where are verified provider contacts available offline?
- Which authorized person can retrieve each module?
- How are home and portable amounts reconciled to one total?
- Where is every withdrawal, return, and refill recorded?
- What event triggers recalculation and reset?
- Has another authorized household member completed the no-spend drill?
If an answer depends on one person's memory, one powered device, or an unexplained round number, the payment system is not ready. Fix that dependency before increasing the amount.
Sources
- American Red Cross — Power Outage Safety
- Consumer Financial Protection Bureau — Get Prepared Before a Disaster or Emergency Strikes
- Consumer Financial Protection Bureau — Your Disaster Checklist
- Consumer Financial Protection Bureau — What Happens if My Bank or Credit Union Has an Outage?
- Government of Canada — Emergency Kit Checklist
Frequently Asked
How much emergency cash should a household keep for a power outage?
Should emergency cash be kept in small bills?
Is a second card enough as a payment backup?
What information belongs on an offline payment card?
Sources
- American Red Cross — Power Outage Safety
- Consumer Financial Protection Bureau — Get Prepared Before a Disaster or Emergency Strikes
- Consumer Financial Protection Bureau — Your Disaster Checklist
- Consumer Financial Protection Bureau — What Happens if My Bank or Credit Union Has an Outage?
- Government of Canada — Emergency Kit Checklist
Related guides
How to Build a Home Power Outage Plan for a Long Blackout
Turn separate outage supplies into one tested household sequence for lighting, food, communication, water, temperature control, and recovery.
How to Build a Grab-and-Go Emergency Document Kit
Create a compact, protected document system that remains usable during an evacuation, extended outage, or loss of internet access.
How to Organize and Store Emergency Supplies at Home
Turn scattered emergency supplies into a mapped, labeled home system that stays accessible, countable, and separate from your departure kit.